Tuesday, October 14, 2014

U.S. TIPS market signals rising concerns about disinflation

Slowing global growth, particularly because of weakness in Europe, as well as a surging dollar and plunging oil prices, have spurred selling in TIPS since late summer, disrupting a comeback they had enjoyed in the first eight months of the year. 
TIPS breakevens have been collapsing since early August. In the last three weeks, following the Fed's most recent meeting and an unexpected monthly drop in the benchmark U.S. Consumer Price Index on the same day in mid-September, the downward momentum in breakevens has been at its most intense since the financial crisis. 
Last week, for instance, 10-year breakevens, a gauge of where inflation will be in a decade, fell to their lowest since late 2011. They dropped below the key 2 percent level targeted by the Fed at the end of last month. On Friday, they ended at 1.97 percent. 
Only last week, the International Monetary Fund downgraded its forecast on global growth this year to 3.3 percent from the 3.4 percent it previously expected, and gave worryingly high probabilities for recession and deflation in Europe. 
Recently, though, another factor has emerged to exert more pressure on the inflation outlook: plunging oil prices. Global oil prices late last week hit their lowest levels since 2010 and are now down 25 percent since June.
DYI Comments:  No doubt deflation for Europe has already arrived and has the high probability of exporting retreating prices here in the U.S.  Look for corporate bond prices to go soft (especially junk bonds), conversely, the best credits in the world, Treasury bills, notes, and bonds, especially the 10 and 30 year to move up smartly in price as interest rates decline in lock step with disinflation / deflation expectation.  If this foretells recession with corporate earnings falling off this sky high stock market its wings will be clipped by 45% to 60%.  The flight to quality would be immense dropping interest rates to levels that the most ardent bond bull would only dream of achieving.  In a scenario as this our sentiment indicator for long term bonds would move from Delusional to Max-Optimism ending the bond bull market of a lifetime since Sept. 1981 when 10 year Treasuries peaked at 15.32%.

Market Sentiment

Smart Money buys aggressively!
Capitulation
Despondency--Short Term Bonds
Max-Pessimism *Market Bottoms*MMF
Depression
Hope
Relief *Market returns to Mean* 

Smart Money buys the Dips!
Optimism
Media Attention--Gold
Enthusiasm

Smart Money - Sells the Rallies!
Thrill
Greed
Delusional---Long Term Bonds
Max-Optimism *Market Tops*--REITs
Denial of Problem--U.S. Stocks
Anxiety
Fear
Desperation

Smart Money Buys Aggressively!
Capitulation 

Continuing with this possible scenario short term bond yields will bottom out awaiting higher rates especially what DYI has described as the roaring twenties (2020's) as Boomers exit the work force but still consuming creating a labor shortage.  This labor shortage along with the massive strains on Social Security and Medicare the roaring twenties will be marked as a decade of labor shortages, high taxes and high inflation.
DYI

*************************************

Detroit demolishes its ruins: 'The capitalists will take care of the rest'

Detroit is knocking down 200 houses a week, with 40,000 to go and $1bn in the program. The city’s controversial plan aims to bring more wealthy investors but critics say will drive out black residents
Detroit
Lawrence Payne walks past two abandoned houses in the Six Mile Gratiot neighborhood of Detroit. The city has an estimated 78,000 abandoned buildings across its 142 square miles. Photograph: Andrew Burton/Getty Images
Shervonne Colvin is ecstatic. This spring, one streetlight was turned back on at the end of her block. Last month, almost one third of her block was razed to the ground by demolition trucks. 
That would hardly excite most city dwellers, but Colvin doesn’t live in just any city. She lives in Detroit, where municipal neglect has become customary. Detroit has been the unwitting star of a photo subgenre christened “ruin porn”, with fans in all corners of the world – except in its native hometown. Two years ago – the same year Forbes named Detroit the most dangerous city in America – local media reported that abandoned homes had become dumping grounds for dead bodies.
Good riddance to that, say residents.
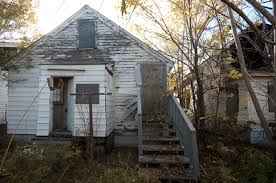
DYI Comment: Whether or not Detroit achieves economic growth doing away with the urban blight is an total God Send for those living there.  The demolition of 200 homes per week is at threshold where the citizens of Detroit are able to see some achievement taking place with a city so use to set backs, corruption, and incompetency.  This is nothing more than a breath of fresh air.  
 
Typical ruins that can be found in Detroit.  By cleaning up the blight Detroit can move onto other pressing problems.
DYI

Monday, October 13, 2014

Life on the Line at Derby Line, Vermont


In the case of the town/s of Derby Line, Vermont/Stanstead, Quebec, the border runs right through the community, cutting through the street grid, and even buildings as well, creating an unusual international zone, where behavior is affected in some interesting ways.In the two-sided town of Derby Line/Stanstead there are two streets that cross the line without any checkpoints. Technically, any time anyone crosses the international line, they are subject to having to report, in person, to a port of entry inspection station for the country they are entering. This makes traffic on the streets that cross the line without a checkpoint, Maple Street/Rue Ball and Pelow Hill/Rue Lee, fairly light, as it is more convenient to cross at Main Street/Rue Dufferin, where checkpoints are often set up for “drive thru” service.
This appears to be Pelow Hill Rd. USA at the stop sign going left or right is Caswell Ave.  After leaving the U.S. the name changes to Lee Rd. or in French as Rue Lee.

This barrier put in place on Rue Lee (Lee Rd. and Maple St.) separates the town of Stanstead from Derby Line

When the international line crosses through a building, a different set of rules applies. Residents of the small apartment building in Derby Line/Stanstead do not need to report if they cross the line inside the building. They only need to report if they leave out the side of the building that opens on to a different country than the one they entered the building from. The building’s interior ends up being an international space, a bubble in the otherwise nearly infinitely thin international line.The most prominent building on the line is the Haskell Free Library and Opera House. It was built intentionally on the border in 1901, as a gift to the community, and a symbol of international harmony. The entrances, one leading into the library, and the other heading up the stairs to the opera house/theater, however, are in the United States.

 
The Haskell Free Library and Opera House which is in use today.


Haskell Free Library and Opera House.


The library reading area and yes that black line is the border.


Two ladies in the library enjoying a cup of coffee (international roast blend??)


Up stairs to the Opera House.


A must have photo for all of the tourists.


Map of the border cutting through the buildings.


Canusa Avenue in Quebec. Canada is on the left, the USA on the right. (Photo: Doug Murray)
Canusa Avenue (Can - USA) those living in the their homes in the U.S. in order to go to work (or drive any where) must enter Canada as Canusa Ave. is owned and maintain by Stanstead Quebec

After 9-11 these two border towns have been turned upside down as the U.S. Homeland Security and the Border Patrol (ICE) have clamped down on the locals movement between the two countries.  As you might suspect those living there (Border Line/Stanstead) have relatives on both sides of the border making it a hassle to visit especially when they live within walking distance yet have to drive to a border check point.  This has been especially difficult on the young people of the two towns.

Forbidden teen lovers (according to Immigration and Naturalization) forced to meet on the sly at the library.

Facing an Uptick in Crime, a Canadian Border Town "Secures" Its Last Open Crossing Into Vermont


But here’s a twist: It wasn’t the U.S. Border Patrol that insisted on the stopgap measure that will likely become more permanent; the call for tighter security came from the Royal Canadian Mounted Police. 
That’s because Canada arguably has more reason for concern. According to a 2010 threat assessment report from the Integrated Border Enforcement Team — a cooperative force of agents from both sides of the border — 2009 marked the third consecutive year in which more people were detained for illegally crossing the border with the intention of entering Canada rather than the United States. Authorities say many of those caught are seeking asylum in a country largely regarded as friendlier to immigrants than its neighbor to the south.
Stanstead and Derby Line have long shared municipal services such as water and sewer lines. Residents recall the days when crisscrossing the international boundary was as simple as a smile and a wave to the border guards. But security along the 4000-mile northern border tightened after September 11, 2001.

DYI 

Friday, October 10, 2014

Not a Stock Market Bubble?....I Beg to Differ!

Opinion: This simply can’t be a stock market bubble


Unfortunately for the so-called permabears, this is not a stock market bubble. Corporate and economic reports show strength across many sectors.Here are five reasons to have faith that the recent softness in the stock market is not a sign that a bubble is popping. 
Data is good: The biggest problem with bubble talk is that it ignores the facts. For instance, the unemployment rate is at 6.1% — the lowest since September 2008. And while bubble believers like to claim this is just from people leaving the labor force, the Fed noted in July that new jobs among the long-term unemployed accounted for 88% of the drop in the unemployment rate this year. I’ll repeat that: The continued decline in unemployment is because those out of work for more than six months are finally finding jobs.Also note that second-quarter GDP expanded at a brisk 4.2% pace, residential home construction in August was up 8% over a year earlier, and so on. But chances are if you believe there’s a bubble, you think these statistics are all lies anyway.

Labor Participation Rate Drops To 36 Year Low; Record 92.6 Million Americans Not In Labor Force


While by now everyone should know the answer, for those curious why the US unemployment rate just slid once more to a meager 5.9%, the lowest print since the summer of 2008, the answer is the same one we have shown every month since 2010: the collapse in the labor force participation rate, which in September slid from an already three decade low 62.8% to 62.7% - the lowest in over 36 years, matching the February 1978 lows. And while according to the Household Survey, 232,000 people found jobs, what is more disturbing is that the people not in the labor force, rose to a new record high, increasing by 315,000 to 92.6 million!

And that's how you get a fresh cycle low in the unemployment rate.
DYI Comment:  The chart below speaks for itself.


Skepticism, not exuberance: Alan Greenspan coined the phrase “irrational exuberance” in reference to the dot-com bubble in 1996, and the two words have been synonymous with bubbles ever since. But there is no evidence of irrational exuberance today. Even if you want to gloss over all the material improvements in the economy, let’s simply consider the preponderance of bubble talk and skepticism that’s out there — as evidenced by the headlines “G20 finance ministers add to fears of a stock-market bubble” on Yahoo! Finance and “Is the stock market bubble of 2014 ready to burst?” here on MarketWatch. You can find even more on sites like ZeroHedge or in CNBC clips from the permabear du jour. The volume of this chatter says a lot about the lack of exuberance.

DYI Continues:  Admittedly there is not out right exuberance but there is massive complacency in all market sectors.  Plus, due to the Fed's sub atomic low interest rates they have driven savers into seeking yield without the knowledge of risk.  Basic savers have been herded into the markets even though it is out of desperation, not greed, the effect is the same.  These are the "last in", basic savers, signifying the formation of a market top.

Valuations are fair: Let’s look beyond macro data and broad sentiment and get into the market itself. A common canard among the bubble crowd is that stocks are grossly overvalued, but a closer look reveals that’s simply not the case. The forward price-to-earnings ratio of the S&P 500 is about 16.8 — high relative to the past few years and with select periods in history, but well below the 15-year average, according to data from market research firm FactSet.Remember, forward earnings estimates can often be way off. And, of course, the S&P 500 was trading at a low multiple during 2008 and 2009 when the global economy was melting down and earnings forecasts needed to move lower. This is not to say stocks are a bargain; it’s just that valuations are fair. And a choppy, fairly valued market is by no means a sign of a bubble.

Market Cap to GDP: The Buffett Valuation Indicator

Click to View

DYI Continues:  Valuations are Fair???  The market it now more than 2.5 standard deviations above the mean.  Market valuation to be fair would be at its mean which is a long way down from this very expensive stock market.

OR....

The current S&P 500 dividend yield is 2.01% this foretells a 10 year estimated average annual return of  1.3%.  That is less than the return on 10 year Treasuries at 2.34%.


Estimated 10yr return on Stocks

Using 5.4% as the historical growth rate of dividends and 4.0% as the ending yield.

Starting Yield*---------return**
1.0%-----------------------(-5.7%)
1.5%-----------------------(-1.7%) 

2.0%------------1.3%   You are Here!

2.5%------------------------3.8%

3.0%------------------------5.9%
3.5%------------------------7.8%
4.0%------------------------9.4%
4.5%-----------------------10.9%

5.0%-----------------------12.3%
5.5%-----------------------13.6%
6.0%-----------------------14.8%
6.5%-----------------------15.9%

7.0%-----------------------17.0%
7.5%-----------------------18.0%
8.0%-----------------------19.0%

*Starting dividend yield of the S&P 500-**10yr estimated average annual rate of return.

Fed tightening isn’t a bad thing: In case you missed it, last week I did a deep dive into how stocks have performed during periods of rising interest rates. And since 1960, almost every period of rising rates has been accompanied by rising stocks. The reasoning is simple: The Federal Reserve loosens policy when times are bad, and tightens when the growth outlook is good. The bottom line is that unemployment is falling and businesses are slowly increasing spending, not cutting back. This is not the “stagflation” of the 1970s. The economy is growing, and inflation is below 2% and hasn’t been above 3% since late 2011. Rather than see the Fed as the cause of more trouble, investors should instead see overtures at tightening as a sign of confidence in the economy and the market at large.
DYI Continues:  Take a look above at the Buffett Valuation Indicator for the 1950's and 1960's for a good portion of those markets were BELOW the mean of the market, interest rates had no effect upon the outcome.  Currently today with a sky high market increasing interest rates will create a competitive environment for stocks as future returns on bonds will be enhanced due to higher rates.

Additional Articles:

Strategist Albert Edwards warns again market may have peaked

Noted stock market bear points to increasing nervousness and volatility
 All investors have a sure-fire signal for when to liquidate their portfolios and head for the hills. We highlight one investor's concern that markets are a 'basket case'. Certainly you can feel the increasing nervousness in the market. Volatilities are definitely on the rise. 

Institutional investors are also getting increasingly nervous that we have reached the end of the road and a major market top may be forming in equities. Notwithstanding particularly concerning economic data out of the formerly reliably robust Chinese and German economies, many market commentators are pointing out that US inflation expectations have now slid to levels that previously triggered the Fed to enact QE - yet there seems to be absolutely no prospect of that occurring currently. Quite the reverse.
 

So maybe it's time to stop dancing and sit this one out. Am I calling a top? What's the point? As an uber-bear I am used to being called a stopped clock. By contrast the market embraces a bullish forecaster however often they are shown to be overly optimistic. The IMF's forecasts for world growth have just been published and guess what - it sees world growth rebounding, just as it has done consistently for the last few years! The market doesn't care that the IMF has been serially wrong and that its forecasts resemble a series of hockey sticks (H/T Zero Hedge). The market loves a bull, even if it is a stopped clock too.
  
And who can expect the same growth rate as we had over the last 50 years? From ‘bond king’ Bill Gross: 
Growth in the US and elsewhere has been facilitated in the past 30 years by the expansion of credit and leverage. Once capitalists recognize that they can’t continue to accumulate leverage at the same pace, growth slows. Demographics also are contributing to diminished economic growth. The boomers aren’t booming. They are getting older and retiring. 
Most boomers need health care, but they don’t need another house or a third car. The aging of our society is putting curbs on economic growth. Thirdly, technology is a boon and a wonder, but it also has eliminated jobs that aren’t being replaced at the same pace. Apple is a wonderful company, but it doesn’t hire as many people as the old General Motors. 
Finally, globalization is an issue. The US has been the world leader in globalization since the end of World War II. We have benefited from mercantilistic expansion, and because the dollar has been the reserve currency. Now things are turning sour elsewhere. When you fly into headwinds, you fly at a different speed. 
We’ve spent our entire life in a credit expansion. We began life when the cork came out of the credit jug. We’ve all been pulling hard on it ever since. 
Credit juiced up the economy…and the stock market. Heck, we’ve lived on it. We’ve taken TVs from China. Autos from Japan. Wine from France and Italy. 
‘Hey, we’ll pay you later,’ we said. 
What if ‘later’ were now? 
Regards,
Bill Bonner For The Daily Reckoning Australia

Mercedes Is Making a Self-Driving Semi to Change the Future of Shipping


The latest truck concept from Mercedes-Benz doesn’t look like anything crazy. Its design is a bit unusual, and it’s loaded up with LEDs instead of headlights and cameras instead of side mirrors. But those modest tweaks to conventional design hide the fact that this is a serious bid to revolutionize the trucking industry. That’s because the “Future Truck 2025″ drives itself. And while it’s a prototype, Mercedes is serious about spending the next decade getting it—and us—ready for commercial use. 
Autonomous driving is nothing new for trucks in agricultural and military applications, and should be available for passenger cars by 2020. But trucks that share our highways are tempting candidates for shedding their human component: Highway driving is easy for computers but dangerous for us, especially when big machines are involved. In 2012, according to NHTSA, 333,000 large trucks were in crashes in the US. Those accidents killed nearly 4,000 people, the vast majority of whom were riding in passenger vehicles. Regulators have trouble ensuring that drivers get adequate rest, and the trucking industry has fought back against regulation.
 DYI

Tuesday, October 7, 2014

Lunar Eclipse to Veil Moon Red in Predawn Hours of Wednesday

In the predawn hours of Oct. 8, early risers and restless souls weary from insomnia are in for a rare spectacle as the Hunter's Moon glows a coppery red, and is veiled by Earth's great shadow. 
Wednesday's total lunar eclipse, set to begin a little after 5 a.m. EDT, will be the second of four consecutive "blood moons" to be visible in the United States during a two-year time span.
DYI Comment:  I'll be getting up early; this will be a sight to be seen! 


John P. Hussman, Ph.D.

A final note: There is a danger in ignoring the concerns of value-conscious investors as a bubble proceeds. The danger is that the longer these concerns are “proven wrong” by further advances, the more severely they are likely to be proven correct by an even deeper loss over the completion of the cycle. Roger Babson offers a useful lesson in that regard. Babson, whose first rule of investing was to “keep speculation and investments separate,” is known not only for founding Babson College in Massachusetts, but also for a speech at the National Business Conference on September 5, 1929, at the peak of the market, saying “sooner or later a crash is coming, and it may be terrific.” 
The back-story, however, is that Babson’s presentation began as follows: “I’m about to repeat what I said at this time last year, and the year before…” The fact is that Babson had been “proven wrong” by an advance that had taken stocks relentlessly higher during the preceding years. Over the next 10 weeks, all of those market gains would be erased. From the low of the 1929 plunge, the stock market would then lose an additional 75% of its value by its eventual bottom in 1932 because of add-on policy errors that resulted in the Great Depression. As a side note, those policy errors were not that banks were allowed to fail, but that policy makers allowed them to fail in a disorganized way, forcing loans to be called in rather than taking banks into receivership and restructuring existing debt. It's a distinction our own policy makers still haven't learned, and simply obscured and papered over in the 2008-2009 crisis through distortionary monetary policy, bailouts, and FASB accounting changes. As a consequence, the debt overhang is still very much intact, as the Center for Economic Policy Research recently warned in its 16th annual Geneva Report. But that's now a problem for another day. 
In any event, be careful in believing that a market advance “proves” concerns about valuations wrong. What further advances actually do is simply extend the scope of the potential losses that are likely to follow.  That lesson has been repeated across history. The chart below offers a visual of this story, and may serve as a useful reminder that valuation concerns are generally not durably proven wrong by further advances, particularly when market valuation concerns have been ignored for a long while.
***************************** 

Fred's Intelligent Bear Site brought to you by Fred Filskov. Public, private, and commercial distribution of this material is permitted as long as a link to this site is attached.
**************************


Fred's Intelligent Bear Site brought to you by Fred Filskov. Public, private, and commercial distribution of this material is permitted as long as a link to this site is attached.


How ugly will gold's selloff get?

A break below key support $1,180 would spell further pain for gold, said Chris Weston, chief market strategist at IG (London Stock Exchange: IGG-GB). Gold fell to the $1,180 level twice last year, in the second and fourth quarter, but rebounded on both occasions. 
"If we get break of $1,180, $1,100 is on the cards before year-end," Weston told CNBC. "There's a perfect storm for gold. Inflation expectations in the U.S., Europe and Japan - three of the biggest economies - have been falling. There's no reason to hedge yourself." 
"Gold is oversold at this level. I think it's an overreaction to U.S. dollar strength," he said. U.S. dollar strength is set to ease, said Su, who expects Federal Reserve Chair Janet Yellen will soon reassure investors that the first rate hike is still some time away. 
"I think there will be a rebound driven by short-covering," he said, predicting that gold will rise to $1,250-$1,300 by year-end.

DYI Comments:  Finally a break in prices for one of our four not so uncorrelated assets due to the Fed's sub atomic low interest rates.  Investors (and many bank saver's pushed into investments) in their "zeal for yield" have pushed all asset prices to the heavens.  Normally at least one our four assets (Stocks, REIT's,Gold, Lt. Bonds) would be in the bargain range boding well for future returns. As an example, at the top of the 2000 market for stocks, gold and gold mining stocks along with REIT's and long term bonds (especially 30 year T bonds) were a screaming bargain.  Currently today no such bargains exist.  In time these totally different asset categories will go their separate ways despite the Fed's meddling and bargains will present themselves.  Unfortunately "The Great Wait Continues!" [Currently today it is not the return on your money but the return OF your money.]

DYI    
******************************

Best of Times, Worst of Times

Meb Faber: The U.S. market is a little bit expensive. And one of the challenges of the valuation is that people want to fall into one of two camps. They either want to believe that things are cheap (“It’s screaming buy!”) or that things are expensive (“It’s going to crash!”). People think in very binary terms, and they hate thinking in terms of it being a spectrum of future probabilities. 
It’s boring to hear, but the more the market goes up, the fewer future returns there are going to be over the next, say, 10 years. The more it goes down, the higher the returns will be. We expect future returns to be in the 4 to 5 percent nominal range going forward. 
It’s not horrific. It’s better than bonds. But you run into some problems as the market gets more expensive. The higher it gets, the higher the chance you have of a large drawdown. 
There’s a study out now that tracked the median stock valuation for the S&P 500, and on a price-to-sales basis, going back to 1960s, it’s the highest it’s ever been—ever! 
The good news is most of the rest of the world is really cheap, and in some places, it’s exceptionally cheap. In our global value fund, we look at the bottom quartile of developed and emerging countries, and that bucket is the cheapest it’s been since the bottom in 2009, the bottom of 2003 and the early 1980s. And if you wondered what the three best times to invest in our lifetime are, those are pretty good starting points.
DYI Comments:  If I'm able to find quality stats for foreign markets DYI will apply our averaging formula to those markets until then we will stick with our four domestic assets.   

*************************************
*************************************

The New Normal for the American Dream – 3 Cornerstones: Low wage jobs, high levels of college debt, and a retirement that consists of working until you pass away.


There seems to be a growing acceptance that the American Dream is hardly as accessible as it once was. Low wage jobs, higher education tuition pushing many into untenable levels of debt, and a new vision of retirement all seem to connect into one new theme. The new theme revolves on a much more challenging road in achieving the American Dream. The majority of working Americans have no sizable portion of stock wealth. In fact, close to 90 percent of stock wealth is in the hands of 10 percent of the population. That is why in spite of the rise of the stock market by 200 percent since 2009, many Americans remain gloomy when it comes to the economy. They are merely spectators to the high flying charts of Wall Street. Most Americans do know that their wages are stagnant, that food costs are jumping, healthcare is anything but affordable, and the road to a college education is paved with high levels of debt. Even the cornerstone of the American Dream which is a home, is very expensive thanks to hot money flowing into the sector and crowding out regular home buyers and pushing the home ownership rate to multi-decade lows. What is the New Normal when it comes to the American Dream?
new america
student-debt-household-service
1 out of 3 Americans have no savings at all. Half of the country is living paycheck to paycheck. Most retirees are going to rely on Social Security as their primary source of income in retirement. This is why for most of the country, the new retirement is no retirement. Many will be working until their hearts stop beating.
 **************************************

Borrowing from 401(k) can cost more than you think

The number of investors borrowing from their 401(k)s has been steadily increasing for more than a decade. Today, more than one in five people, or 22.5% of Fidelity's 401(k) investors, borrow against their retirement savings, up from 18.7% in 2000, according to Fidelity's analysis of 13 million investors.
What's most concerning, says Jeanne Thompson, vice president of thought leadership for Fidelity, is that the analysis finds that a significant portion of those who borrow aren't able to maintain their previous savings rate: 40% of borrowers reduce their savings rate, and of those, more than a third stop contributing to their 401(k) altogether within five years of taking a loan.
 They may also be in the most trouble when it comes to paying the loans back. Known for only staying at companies a few years, Gen Y could be hurting their retirement savings even more when they leave a company, which is when 401(k) loans have to be paid off. Those who can't pay off their loans in full still have to pay all taxes owed on the balance and a 10% penalty if they're younger than 59.5, Thompson says.
DYI Comment:  For first time home buyers here is my take on borrowing money from your 401k. Those who are purchasing a home with a cost at or below two times your income then using monies from your 401k to drive down the mortgage closer to one time income or less; this is not only perfectly acceptable but a very conservative strategy.  15 year mortgage or if possible 10 year loan you can can have your house free and clear very quickly.  Believe me their is nothing like having a paid for house especially when the next economic downturn arrives.

DYI 


Friday, October 3, 2014

“Yo” – This Market is Set For a Major Correction

Wall Street came to a halt recently, as Chinese e-commerce giant Alibaba made its Initial Public Offering debut.  The media became myopically focused over this so-called “historic event” and by its celebrity founder Jack Ma.  By the time the closing bell had rung, the hype and fanfare propelled Alibaba up 36 percent on its first day of trading and caused the world’s largest IPO to display a market cap worth $231 billion.  The investing public seems to have forgotten the dangers associated with disregarding valuation metrics—Alibaba is trading at a Price to Book value ratio north of 27! 
But it’s not just irrational investments, such as Yo, and overhyped IPO’s, that are signaling a top to this market.  There are technical indicators in the market that are also setting off loud warning bells.  The breadth of the market is troubling to say the least, with nearly 50 percent of stocks in the NASDAQ down more than 20 percent from their peak in the last 12 months.  Additionally, more than 40 percent have fallen that much in the Russell 2000 Index.   In fact, the Russell 2000 index of smaller companies is now down over 4 percent on the year, and has in technical terms reached a “death cross”. A death cross occurs when a stock or index’s 50-day moving average trend line dips below its 200-day moving average; and is a sign momentum is fading. 
It’s clear as the Federal Reserve reins in its economic stimulus plans that the appetite for risk is narrowing.  QE III totals $1.7 trillion worth of Treasury and Mortgage Backed Security purchases and this program ends in October. And the Fed’s massive money printing scheme, which resulted in record-low interest rates for the last 6 years, has manifested in stock, real estate and bond bubbles occurring all at the same time.

Regression to Trend: A Perspective on Long-Term Market Performance

The peak in 2000 marked an unprecedented 148% overshooting of the trend — nearly double the overshoot in 1929. The index had been above trend for two decades, with one exception: it dipped about 13% below trend briefly in March of 2009. But at the beginning of October 2014, it is 89% above trend, up from 85% above trend the month before. In sharp contrast, the major troughs of the past saw declines in excess of 50% below the trend. If the current S&P 500 were sitting squarely on the regression, it would be around the 1057 level. If the index should decline over the next few years to a level comparable to previous major bottoms, it would fall to the low 500 range.

Secular Bull and Bear Markets

Ben Graham Corner

Margin of Safety!


Central Concept of Investment for the purchase of Common Stocks.
"The danger to investors lies in concentrating their purchases in the upper levels of the market..."

Stocks compared to bonds:
Earnings Yield Coverage Ratio - [EYC Ratio]

EYC Ratio = [ (1/PE10) x 100] x 1.075] / Bond Rate
1.75 plus: Safe for large lump sums & DCA
1.30 plus: Safe for DCA

1.29 or less: Mid-Point - Hold stocks and purchase bonds.

1.00 or less: Sell stocks - rebalance portfolio - Re-think stock/bond allocation.

Current EYC Ratio: 1.03
As of 10-1-14

PE10 as report by Multpl.com
DCA is Dollar Cost Averaging.

PE10  .........26.14
Bond Rate...3.98%


Over a ten-year period the typical excess of stock earnings power over bond interest may aggregate 4/3 of the price paid. This figure is sufficient to provide a very real margin of safety--which, under favorable conditions, will prevent or minimize a loss......If the purchases are made at the average level of the market over a span of years, the prices paid should carry with them assurance of an adequate margin of safety.  The danger to investors lies in concentrating their purchases in the upper levels of the market.....

Common Sense Investing:
The Papers of Benjamin Graham
Benjamin Graham

DYI