Rob Larson’s Hit Piece!
Comments
by DYI
The Good,
the Bad, and the Downright Ugly
Dave Ramsey Says Capitalism’s Failings Are Actually Your Fault
The financial guru advocates blaming yourself for society-wide economic crises, and abasing yourself to pay debts no matter what.
DYI: I’ve watched on YouTube (10+ years) well over 1,000 “call
ins” to his radio show and I’ve never heard Dave become callous with people
seeking his advice. Oh there are times a
bit of tough love especially those with income way above the national average
and yet they make themselves one huge pile of mess (all of their own doing).
I’ll get into later his snowball method for paying off debts and his so called misunderstanding of how people get into as Mr. Larson states “Dark Financial Waters!”
Ramsey’s advice will sound familiar to anyone who has encountered other prominent self-help finance gurus, like the prominent vampiric-eyed finance coach Suze Orman. It’s a standard self-reliance line, heard on any cable show discussing home finances, urging individuals to pull their way up out of debt. Paired with the traditional U.S. Protestant work ethic, where God helps those who help themselves, Ramsey’s show strikes a chord in an audience raised by parents and their church to believe that the rich must have worked very hard and the poor should get a job.
DYI: Good Lord the author would have you believe that no one is capable of moving forward financially. If you’re poor you’ll always be poor and never capable of moving up at least to the working class or lower middle class. So now the Protestant work ethic is a bad thing? And then automatically shifts to the super rich?
Moving on…
Ramsey professes an anti-debt absolutism, claiming no one should ever use credit cards or 30-year mortgages, because of debt’s long-term economic and personal costs. But this advice is of limited value in a disaster-prone economy where workers have had their share of the pie whittled down year after year, to the point that 29 percent of Americans now say they could not pay an emergency cost of over $400. Turning to debt at such moments is tough to avoid, but Ramsey portrays it to his massive listener base as a personal failing, and offers dubious advice to get out of it.
DYI: The alternative according to Larson is piling on more debt paying a mountain of interest to the bankers who are some of the richest men and women on the planet!?? These are the same people Larson has a huge problem with and yet is promoting giving peoples hard earned money to this super rich class!??
Moving on...
Ramsey’s debt absolutist line is extreme, even by the standards of the massive personal finance guru marketplace. He insists that you don’t need credit cards, that your credit rating is therefore meaningless, and he argues that families should only buy a house with a 15-year mortgage and down payment of at least 10 percent.
But 15-year mortgages come with far higher monthly payments, and avoiding all other debt is often impossible for many people, from accident victims to consumers confronting inflation. To look back at the stagnating buying power of the median U.S. household over the last several decades, it’s just fatuous to contend that people can realistically go without debt. How people are supposed to cope with the evaporation of income after being laid off, or clear the mountain of medical bills left from an accident or illness, is only lightly addressed on Ramsey’s show.
DYI: Why a
15 year loan? Home owners move on
average every 7 to 10 years with the 15 year loan a vast majority of the
property will be paid off (almost nothing with a 30 year) rolling those monies
into the new home of similar cost within a few years they’ll have a paid off
house.
Moving on…

DYI: I went to the link that Larson provided (see chart above), his
proof of how sucky the U.S. economy is suppose to be comparing from 1971 to
2023. Let’s take a look – shall we…1971
to 2023 – the lower middle class increased by 11%. The middle, middle class has decreased by 16%
and the upper middle class has increased by a whopping 73%!
You would be let to believe from Larson that
the lower middle class would have ballooned significantly higher than an 11%
increase from 27% to 30%. The middle,
middle class is where damage has occurred by a drop of 16% going from 61% to
51%. Needless to say (but I’ll say it
anyway) 51% remains a strong number when taken into account the upper middle
class has jump a massive 73% increase!
In other words the big jump for the upper
middle came primarily from the middle, middle class. So…8 percentage points came from the middle,
middle making their decline only 2% points or a drop of 4%.
Do we have problems as a nation? Of course we do. The middle class has taken a few elbow shots
to the ribs but is a long way off being destroyed.
Moving on…
Instead, Ramsey broadly adopts a standard “you’ll get rich if you work hard, and won’t if you’re lazy” view. But recessions and waves of high inflation are indisputably macroeconomic social trends and it’s frankly ludicrous to make the rock-solidly reliable conservative claim that the poor and indebted are just all thoughtless lazy slackers. Recessions, the irregular but reliable patterns of market retrenchment that have characterized capitalism since its origins, must be accounted for in any serious financial planning, which is usually intended to be long-term, for example planning for retirement. But what kind of long-term planning shrugs off the very real possibility of being forced onto credit cards or payday loans after you and everyone you know gets laid off at the plant in the next downturn?
DYI: Here Mr. Larson is one aspect that I disagree with Ramsey. He advocates a 3 to 6 month emergency fund; I suggest a one year fund with half in a high yield savings account and the other half in a very low downside volatility fund such as The Permanent Portfolio PRPFX. You’re right the economy could tank and one needs to be prepared.
Discussing callers in their 70s who describe needing to work late in life due to a lack of savings, Ramsey said people need to simply spend less when they’re young, and that for younger people these calls should be “God’s direct slap” as a wakeup call for you—so the lives of these elderly citizens are just God’s tools for educating us. After noting people work hard but then spend luxuriously on $750 car payments, Ramsey exclaims “You’re broke because you’re stupid!” Immediately after this he insists people buy life insurance against early death leaving children with nothing. He concludes “I don’t want to be working at McDonald’s when I’m 70, unless it’s the one I own in St. Thomas.”
DYI: WTF????
Working in their 70’s because they’re flat broke except Social Security;
if that is what has to be done so be it.
I’m soon to be 72 and those who I’ve met working in their 70’s many will
tell you they never took saving, investing and debt free lifestyle
seriously. The vast majority simply “blew
it off!” And damn right I hope young
people (20’s and 30’s) see old folks having to work well past their prime and
vow to take their personal finances seriously.
Moving on…
There are few things more annoying than a friend or family member who refuses to take responsibility for actions they’ve taken or things they’ve said that are legitimately harmful or cruel. But here we are talking about assigning personal blame to people for how they cope when swept up by the great forces of economic history, when very few options are available to them. When told a story of a desperate person who steals food during a war, people tend to be more understanding and not to put personal blame on them—only the most hardcore libertarians will say “Why didn’t you plan for this wartime famine and take responsibility for the collapse of your government and economy?” But insisting that people “be grown ups” during major economic contractions is almost as buffoonish.
DYI: The
paragraph above is simply there to fill space along with an attempt to charge
up your emotions to keep you from thinking logically.
Moving on…
This is clear in areas like medical debt, a category where Ramsey’s worldview really falls apart because his usual lines about frugal spending don’t apply. Nobody makes an impulse buy of a replacement organ, or has a frivolous broken bone. Ramsey’s website admits that medical debt “sucks” and makes you feel “hopeless,” and recommends that those struggling with medical debt should prioritize their family’s needs first, carry out the usual godforsaken homework required by private health insurance to make sure your insurer is being billed properly, and then once your debt enters collection to, no joke, “set up a meeting with the hospital administrator or billing department[…] Explain your situation to them in person[…] People can be pretty understanding and compassionate when you’re thankful.” Callers often have medical debt, like Kelly from Indianapolis, who carries a $47,000 balance from her son, who had major issues as a baby, when she had no insurance. Referring to the show’s “baby steps” debt recovery model, she asks the dystopian question, “Where would I end up putting my son’s medical debt, within our other debt?” These callers get helpfully told to make these implausible-sounding appointments with senior hospital chain executives and ask for a settlement to pay “pennies on the dollar.” Regrettably, Ramsey seems not to realize that hospital executives are officers of incorporated businesses who have limited flexibility to just waive large debts, even if you’re somehow able to hack through phone hold trees to get into their office. His advice amounts to groveling and hoping for the best.
DYI: No doubt medical costs and the debt it creates are outrageous! Let’s get serious the vast majority of people calling into his show do not have medical debt they have consumer debt of their own doing either individually or spouse who is a spender.
Moving on…
Particularly annoying in this context is Ramsey’s frequent shaming of bankruptcy, which is the anti-debt solution for many people. Filing for personal bankruptcy allows a person or business in too much debt to have their loans legally voided, after a court process that forces the filer to sell most of their assets in order to partially repay the lenders. Personal filings have a lifetime limit, so a person can only declare once. For people with major medical bills, huge credit card balances, or other realistically unpayable debt, bankruptcy is a legitimate option. (Note, though, that not all forms of debt can be expunged in bankruptcy, most prominently student loan debt.)
Ramsey tends to consider bankruptcy a form of giving up or even cheating in the battle to get out of debt, suggesting on the air that debtors should pay those debts off to poor needy credit card networks rather than take the “easy way out”—which, again, is not easy and involves an extensive court process and surrendering most of your assets. He adds on his website that bankruptcy should be “your very last option.” This concept of moral obligations toward debt, that your failure to pay debts indicates a selfish or lazy personal failing, is an odd contrast with corporate bankruptcy, which companies regularly enter into and exit from after restructurings that are seen as regrettable but legitimate business measures. (In fact, the business blog CFO Dive reports that corporate bankruptcies currently “hover at [a] 16-year high,” with 372 companies filing this year as of June.) Ramsey’s website’s more detached primer on the subject describes the real limits of the process, before mentioning it can be avoided by speaking to a “financial counselor,” with a link provided to his affiliated financial therapists.
Ramsey himself, of course, filed for Chapter 7 bankruptcy in 1988 after his early real estate investments collapsed when the market crashed and his lender called in his short-term loans. Yet even here Ramsey puts the blame on the individual, as his website bio recounts his struggles with those loans by saying “I’m the idiot who signed up for the trip.”
DYI: Over my many decades when talking to ex-business owners who failed the vast majority stated they made multiple poor decisions. Over use of debt and a lack of an emergency fund is the number 1 through 10 for their business failure. I’ve found that the majority of these folks are very good at what they do within that chosen career but when it comes to the business portion – the handling of the money is almost 100% of the problem.
Also the vast majority of these callers if they sell a majority of their assets they can pay off those debts. Remember in bankruptcy the court will sell off those assets as well. Bankruptcy is no panacea unless the debts are so high an individual or couple will have no other choice for bankruptcy. That is the exception not the norm that Larson is attempting to peddle.
Moving on…
A real loyalist of capitalism will blame themselves before they blame the system. Despite his household-name status, Ramsey’s actual personal financial advice is not great. Personal finance is often derided for offering simple advice anyone could think of—cut spending on non-necessities, pay off debts, save as much as possible—but that requires decent income in the first place. The entire premise of personal finance is based on what you can do personally, but you can’t personally end a recession or increase the labor share of national income. Your individual financial decisions most definitely will play a big role in your life, but so will the great impersonal macroeconomic forces of our times. But Ramsey’s particular approach somehow fails to clear even this low bar.
DYI: Dave
Ramsey has stated so many times its impossible to count that he is in the micro
business not the macro business. Micro
is in the individual improving his or hers lot within the current economic
environment we have today.
The macro business is Larson’s business
discussing our present day economic conditions and his solutions that I assume
he has (so far I've haven't read one suggestion).
I hoping if you’ve read this far, Larson is
using Ramsey’s fame as a springboard for his website to generate clicks
(admittedly I’m doing it as well).
Moving on…
To be clear, getting out of personal debt is obviously good and important. After all, we socialists tend to see debt as a tool of capitalism in which workers who are paid too little for their labor must borrow money instead, making them yet more dependent on the forces of capital. Debt leaves you vulnerable to coercion: just this week, an op-ed in the Jerusalem Post recommended using the promise of debt relief to pressure young Americans into volunteering to invade Iran. Toward the goal of getting out of debt, most financial advisors recommend prioritizing those debts that have the highest interest rates, like credit cards or cash advances, relative to those with lower rates. The reason is simple mathematics—debts with higher rates cost more to pay off a given amount of the principal than those with lower rates, so knocking off that brutal 20 percent rate on a credit card balance is naturally a higher debt-riddance priority than a 6 percent rate on a car loan.
Ramsey, however, insists on a “snowball” method where followers pay off smaller debts first, regardless of the interest rate. “Knocking out that first debt gives you a quick win and builds momentum,” he insists. So he advises paying off initially whatever debt category you have the smallest balance in, for the feeling of accomplishment and agency, rather than prioritizing more expensive debt. Now I suppose there’s a case to be made here, since one thing Ramsey’s callers very reliably express is how hopeless they come to feel when deep in debt. Some see peers on their curated social media accounts flashing costly cars, compare that to their own debt, and say they feel they’re “losing at life;” others feel “trapped” in an unhappy marriage by shared debts. These issues tend to become more acute once people have multiple forms of debt, and even more so when one or more of those debts go into collection, which allows essentially for institutional harassment of borrowers.
Certainly, capitalism has zero compunction about burying people in debt, whether due to low pay relative to expenses, or due to a life event like a health episode, or discovering a loved one ran up debts from a gambling problem. So the Ramsey method recognizes something real when it prioritizes a “snowball method” of building encouragement against debt’s demoralization. But it’s a rock-bottom mathematical fact that this method will also cause borrowers to pay more in the long run. (Frankly I prefer the “Money Momentum” bit from Kids in the Hall.) In terms of straight dollars and cents, paying down debt with higher interest rates is the inarguably most efficient money-conserving approach. Ramsey’s claim is that satisfaction and feelings of accomplishment will increase financial commitment, but again, those are feelings and math is facts and I demand an explanation from conservatives.
DYI: That’s the best you have is a complaining about Dave’s snowball debt payoff method!??
Here’s the Kenneth Royer – owner, chief cook
and bottle washer of this blog – method for debt relief. Pay off the debt! I don’t care if its snowball or paying off the
highest interest rate first and once you’re out of debt stay that way. Build up an emergency fund not just 3 to 6
months extend it out to one year or even more.
Put 6 months in high yielding savings account and the other half (or
more) into a low downside risk investment.
The Permanent Portfolio symbol PRPFAX comes to mind or Vanguard’s
Wellesley Income Fund symbol VWINX.
Moving on…
Ramsey is an evangelical Christian, and fits easily into the mostly conservative wasteland of talk radio, right down to abusing the Bible. As Helaine Olen observes, he likes to quote part of Proverbs: “The borrower is the slave of the lender,” but somehow never mentions the preceding part, reading: “The rich rule over the poor.” (The bit about Jesus casting out the moneylenders with a scourge is also, mysteriously, absent.)
Ramsey has a major presence in evangelical churches. To some it might appear unseemly to go on tour to speak to massive church audiences, ultimately promoting one’s own show, books, and financial advisor network. But Ramsey’s message connects very well to U.S. evangelical Protestantism, with its focus on an individual’s personal relationship with God and using life success as a sign of a person’s virtuous industriousness and prudence, or economic failure as proxies of the sins of sloth and gluttony. Historians like R.H. Tawney have long found that the spread of the Protestant Reformation in northern Europe helped create the conditions for capitalism, as entrepreneurs from ambitious merchants to very early industrialists saw the potential for riches and wanted to see God smiling upon those riches.
The ultimate result is the contemporary self-help Christian marketplace. Ramsey is very much of this common mold, but I do feel he reaches some new depths in gross exploitation of an anti-materialistic religion. For example, the “momentum” method mentioned earlier, which dubiously claims the thrill of settling a debt outweighs the higher costs that will be paid in the long run, is the subject of a book by Ramsey. But the book specifically argues that God is a part of this process, and no joke, offers the following equation:
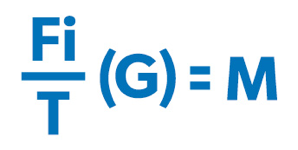
Now folks, if you’re unable to read this equation because you are a pitiful heathen without a degree in Christian Math, luckily, I am here to interpret for you. Ramsey explains his equation reads, and I quote, “Focused Intensity, over Time, multiplied by God, equals Unstoppable Momentum.”
You may find yourself skeptical of this “equation,” and that’s good, because it’s remarkably dumb. Perhaps intended to be at least partially tongue-in-cheek, it nicely illustrates the faith that your personal Protestant God is holding your hand as you slowly pay down that six-figure hospital bill from the time you got T-boned by a teenager with no insurance in a giant SUV.
DYI: Five paragraphs above ranting about the evangelical churches and Dave’s involvement speaking to these churches and yes selling his products as you see as being unseemly. I’ve look at all of his products and none are over priced and to the contrary most are modestly priced. Am I to assume he is harming these people??
The HUGE portion is
Ramsey’s Baby Steps.
Baby Step 1: Save $1,000 for a starter emergency
fund.
Baby Step 2: Tackle all non-home debt using
the debt snowball approach by paying smallest balances first.
Baby Step 3: Build a fully funded emergency
reserve covering 3 to 6 months of expenses.
Baby Step 4: Allocate 15% of income toward
retirement investments.
Baby Step 5: Fund children's college
education goals.
Baby Step 6: Accelerate payoff on your home
mortgage.
Baby Step 7: Grow wealth and practice
generous giving.
A simple plan that anyone can follow.
Moving on…
Certainly Ramsey’s millions of listeners have internalized this outlook—caller after caller rushes to take responsibility to pay the horrifying care bills created by their child with special needs, to take charge of their spouse’s gambling debts, to not let themselves off the hook for leftover debt from a failed business. As much as they seek advice, Ramsey’s listeners are the real source of wisdom on the show, as they are brushstrokes in a rich portrait of the cruelest economic system imaginable, and yet cannot blame themselves for it quickly enough.
DYI: Taking
on a spouse gambling debts? You just
couldn’t help yourself by pumping out your first lie. Dave has never advocated that especially if
the relationship is headed straight to divorce.
Obviously if they are going to stay married and depending on how high
the debt is whether this debt should be discharge in bankruptcy or simply paid
off.
Larson makes it sound like every family has a special needs child! Good Lord man lighten up a bit most folks don't have that situation which is the majority of his callers.
Moving on…
In line with his self-reliant, self-made fortune rhetoric, Ramsey is generally conservative, opposed for example to emergency measures like COVID stimulus payments, but also public aid generally. He claims movements like Occupy Wall Street are “sinful” because they represent “envy,” although he seems to overlook the wild gluttony and greed of the rich that Occupy opposed. He remarked on his show that “We’re always going to have wealth inequality. You can’t fix that,” likening it to some people being taller or prettier than others. Of course, people who are tall don’t have the ability to significantly exert power over society, which the wealthy absolutely do have. And unlike height, wealth can be redistributed through cool public programs.
Ramsey has gone further and claimed that the rising wealth inequality of the U.S. is “not really true,” a remarkable statement by a product-hawking radio host as it contravenes one of the best-established conclusions of the social sciences. Readers familiar with this magazine will recall numerous sources that strongly confirm the ongoing concentration of wealth, from my favorite, the World Inequality Database, to a little operation known as the Federal Reserve, which now maintains the Distributional Financial Accounts, a precious national data set which track the flow of incomes and the levels of wealth in the U.S. Both these and other long-established sources of distributional data strongly converge on the conclusion that the rich are indeed getting richer while the working classes stagnate or decline in purchasing power. Presently, the richest 1 percent of US households are sitting on about 34.8 percent of total wealth nationally, while the poorest 50 percent are standing strong at 1 percent.
Ramsey likes to say that those concerned with the issue are “economically illiterate” since they think the “economic pie” isn’t growing, so a rich person must have taken extra from the poor. This is a typically pathetic reactionary dodge, of course. All the research shows that the capitalist pie is, as usual, growing—it’s just that the huge majority of the gains are going to the already-richest households. The WID, for example, finds that since the 1990s the richest 10 percent of households has seen 3 percent economic growth annually, the richest 0.1 percent of households grew by 5 percent a year, and indeed “the wealthier the individuals, the higher their increase in wealth. The share of wealth for the bottom 50% globally was negative over the period.”
More concretely, the famous RAND corporation ran a “counterfactual” study which estimated what each U.S. income level’s pay would be in 2018 if it had grown at the same rate as the economy did, starting in 1975. Incomes for the 1 percent were lower in this scenario, since their wealth has grown faster than the overall GDP. But for the bottom 25 percent the picture’s different: Their average annual pay was $33,000 in 2018, but if it had grown at the same rate as the economy it would have been about $61,000. That’s a stunning $28,000 every year that goes instead to the already-rich at the top.
In addition to making drably predictable wrong remarks on wealth distribution, Ramsey also has a grotesque idea of housing, treated as an investment asset in the U.S. despite being a necessity for human life. In response to an on-air call, Ramsey mentions that in “the many other properties we own,” if he raises the rent to “market rate, that does not make me a bad Christian. I did not displace the person out of that house if they can no longer afford it, the marketplace did. The economy did.” Just following market orders, people! Capitalists have been hiding behind this sleight-of-hand for years—the market is made up of choices like Ramsey’s, but somehow it’s poor people who make the bad choices, not wealthy landlords. Ramsey adds the family can move to a “cheaper house… a lesser house.”
Ramsey is also opposed to labor unions, even though they’re clearly a major personal finance tool, associated with a “union premium” for worker pay, recently estimated by the Treasury Department at 10 to 15 percent. In a video from 2022, one of his co-hosts gets pretty hot under the collar about unionizing Starbucks workers, and claims “unions are bad for the people” because they charge dues and cause “an unnecessary adversarial tension between employees and company leaders.” Companies should have a nice family vibe, although it’s a family you can be fired from. And worst of all, the union controls what can happen in the workplace, which is bad, because of course work is a total free-for-all where you do what you want, until you get a local. It might also be added that the usually-sympathetic video comments are absolutely cooking the host, Ken Coleman, for having a cozy job behind a desk rambling for a millionaire’s YouTube page. Viewers with experience in unions pointed out that in fact, they’re great for your personal finances:
- “You are just saying this because you are high up in the Ramsey company.”
- “I love my Teamsters benefits.”
- “As a tree trimmer my union (IBEW) has done wonders for me.”
- “I was non union for over 9 years always got cheated with overtime and Job threading for sometimes leaving early to take care of family matters or not staying late when ask to i got tired of it i join a union and life has gotten way better and I’m able to enjoy more time with my family and able to afford to take them out more on vacation.”
- “My father was part of a carpenter’s union that helped him when he was injured on the job and made sure he was taken care of, when he physically couldn’t anymore.”
- “I worked at a ralphs grocery in california when they unionized, i got a $2 raise and my PTO doubled.”
- “I remember meeting a union member for the first time back in the 90s, he was an iron worker, i live in the south with the toughest anti union laws there are so unions are extremely rare here. the guy was a customer, i am looking over his credit app, i get to his salary, and thought it was a mistake, double what i made and 60-70% more than any iron worker i knew, i asked him if that was correct, then just straight up asked “who is this company that pays so good?” the name he put was like AIWA (Ar iron workers) or something, i never heard of them, he answered in one sentence, “its union pay scale.” i was so blown away.”
- “Having worked union and non union in the same industry, there's no comparison in terms of safety, benefits and wages. Unions provide much much more for employees.”
Unions: your #1 personal finance solution!
On the air, Ramsey also reliably repeats the standard hoary right-wing line that government aid like welfare actually makes the poor reliant on government handouts, and therefore public aid makes people poor, not the market. Which is true, because there were no poor people before food stamps. The food stamps program, SNAP, is actually a major poverty-reduction success story, with John Hopkins University research finding it both greatly reduces food insecurity (especially for poor kids) while also freeing up family money for other necessities like rent and utilities. All this, despite providing on average just a few dollars per meal per day to recipients. Ramsey is his most forgettable in this mode, becoming just another talk radio conservative railing against COVID masking or big-spending Washington.
DYI: Our Congress
men and women along with Presidents of BOTH political parties spend money far
worse than any drunken sailor could ever dream!
Congress and Presidents all know they’re backstopped by the Federal
Reserve by their ability to digitally print money into existence to finance a
portion of the debt (currently around 6.5 trillion). But alas this causes inflation to surge
destroying an ever greater portion of one’s pay and if you’re in the working
poor class their paychecks will end up devoid of purchasing power.
The biggest
program to help the poor is by ending inflation!
Advocate and pass a balanced budget amendment to the constitution AND bring back the control of the money supply to the Treasury Department. The Treasury will have the ability systematically to retire the national debt by buying up Treasury bills, notes, and bonds over a period of a few decades. This money creation as long as it is less than improved efficiency in the economy will be non inflationary. Even if some inflation occurs at least the national debt is being reduced, along with interest payments shrinking the cost of the Federal government.

There is no doubt the haves v.s. the have nots has grown wide and continues to grow in that direction, taking on Dave Ramsey solely on the grounds of his political views actually is appropriate, however when it comes to his "MICRO" views you're way off base, so much so, it appears you favor the banking class!
Moving on…
In a society defined by cruel, relentless class warfare, it’s inevitable that self-help and especially money-advice grifters will find a market. And bathed in a commercial culture constantly urging us to spend, indulge, and borrow to pay for it, there is most definitely a role for personal finance education in America, including avoidance of needless debt—but also how to manage that debt which society essentially requires you to have, like car loans or a credit card balance, to keep the family fed and housed.
DYI: What total Bull Shit!
This is what
society REQUIRES??
Used cars
can be bought by saving up the money.
That’s right paying cash for the vehicle saving on the interest
payments. Credit cards necessary for day
to day living expenses Mr. Larson?? That’s a fast way to the poor house since
you’re required to pay the money back to the lending institution.
Moving on…
But figures like Orman and Ramsey have built massive wealthy empires by insisting that poorer people must surrender every petty, fleeting pleasure in order to maintain payments to the richest corporations in the world, from the credit card networks and student loan issuers to the Wall Street entities that supply the capital for it all. Owing a big share of your income to passive investors is simply the Way Things Are, not a result of government and corporate policy choices. Their advice is to take irrational actions, paying down the debt no matter what and binding your idea of the Creator to your revolving credit card balance. And for the dozens of daily callers, Ramsey is ready with Tough Love for their desperate borrowing actions during major historical events like the Great Recession and Covid, less punching down than just stomping down.
Ramsey is a beloved figure among boomer dads across America, but his sweet Southern accent yields bitterly bad advice.
DYI: And Now a Cheap Shot at Boomer Dad’s!
If Larson would
have stuck to his differences between himself and Dave Ramsey’s general overall
economics then his article would have had value. But combine Ramsey’s debt free lifestyle, as
if it is impossible or viewed as a negative with his political views reduces what
little value for Larson’s article.
The biggest problem Larson has with Ramsey is that their respective political views are polar opposite and because of this massive difference Dave will never use his HUGE platform to deliver Larson's message. Within that frustration Larson uses bulling and name calling tactics.
And once again I've read ZERO advice from Larson not even glittering generalities. A CLICK BAIT article working off of Dave Ramsey's fame! I'm doing the same but at least I'm honest about it!
Till Next Time!

No comments:
Post a Comment